
Texas flood insurance
Do I Need Flood Insurance in San Antonio If I’m Not in a Flood Zone?
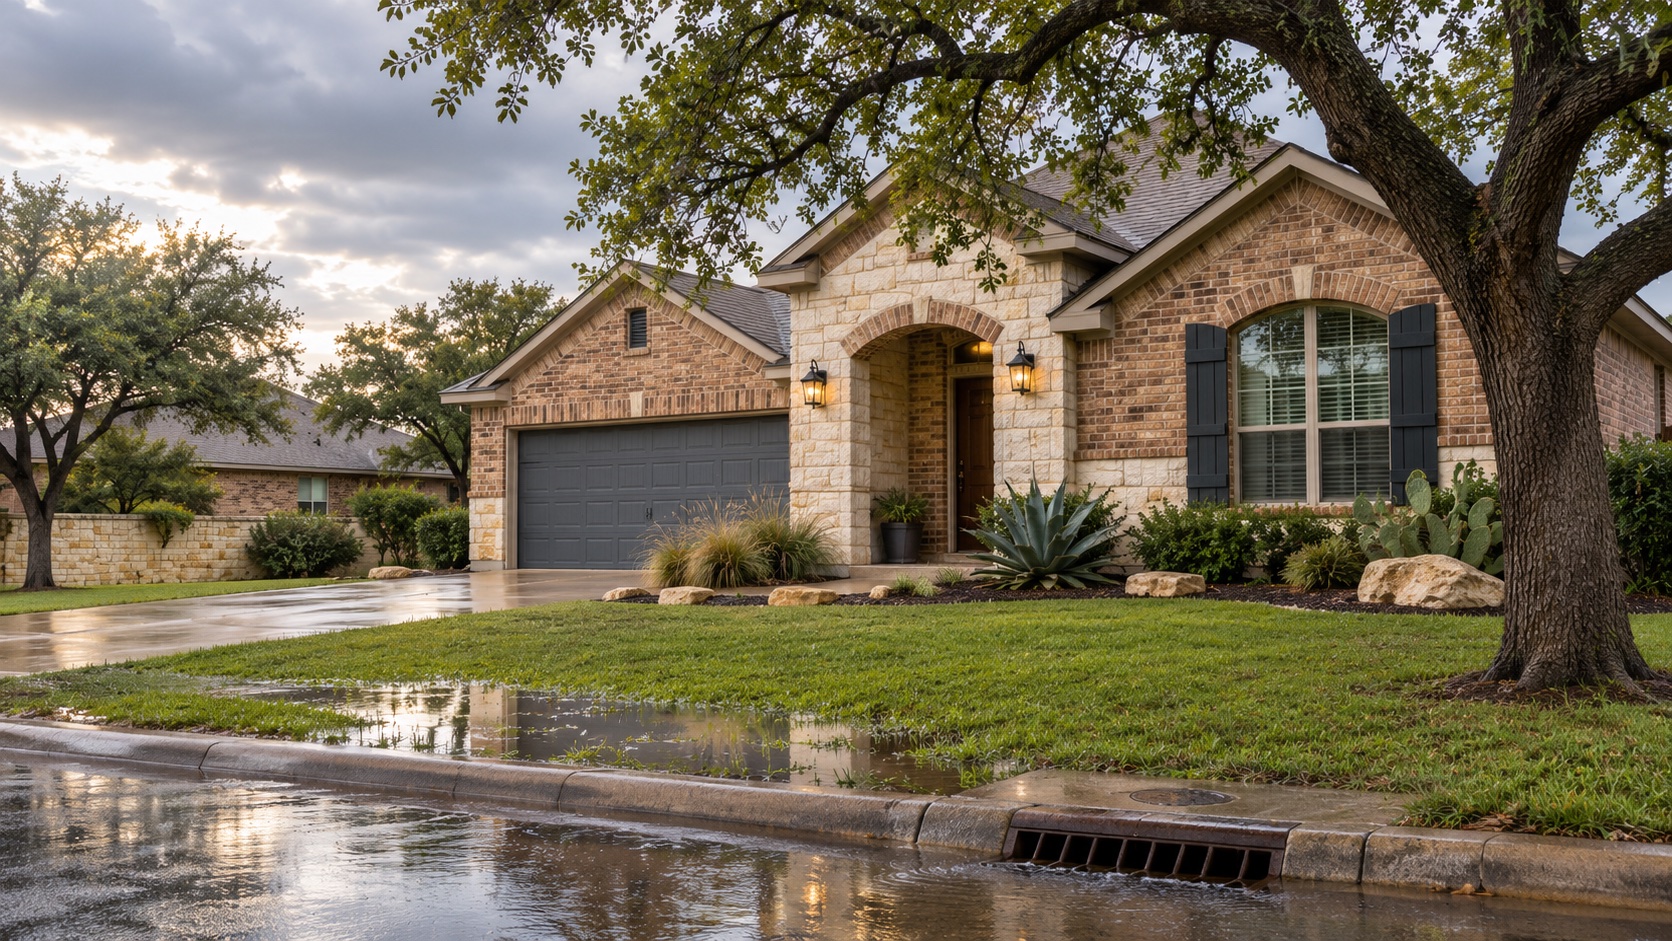
You may still want flood insurance even if your home is outside a mapped high-risk flood area. Most standard homeowners policies do not cover damage from rising floodwater, and lower-risk on a flood map does not mean no risk. In San Antonio and the Hill Country, flash flooding makes this an important question to review before heavy rain arrives.
Does homeowners insurance cover flood damage?
Usually not. Flooding generally involves water overflowing onto normally dry land—for example, runoff from intense rain entering your home. That is different from a sudden indoor plumbing leak, which may be covered under some homeowners policies depending on what happened.
Ask your agent to explain the distinction under your specific policy rather than assuming all water damage is treated the same.
What does it mean if I’m not in a high-risk flood zone?
Flood maps describe levels of risk; they are not a guarantee that flooding cannot happen elsewhere. Texas Department of Insurance guidance notes that a substantial share of National Flood Insurance Program claims occur outside high-risk areas.
A homeowner near a drainage channel, low-water crossing, creek, or fast-growing area in Bexar County may have concerns even without a high-risk designation. Map information and local drainage conditions both deserve attention.
Is flood insurance required if I don’t have a mortgage?
Often no, but it may still be worth considering. Certain lenders require flood insurance for buildings in designated high-risk areas when the loan is federally regulated or backed. A homeowner without a lender requirement can generally choose whether to buy it.
How much does flood insurance cover?
The National Flood Insurance Program offers residential building coverage up to $250,000 and separate contents coverage up to $100,000 for eligible one-to-four-family residential properties. Private flood insurers may offer different limits and terms.
Ask whether your estimate includes building coverage, belongings coverage, deductibles, and exclusions. Don’t assume a flood policy pays for every expense related to a flood; for example, NFIP coverage generally does not pay additional living expenses.
Can I buy flood insurance right before a storm?
Do not count on it. A new NFIP policy generally has a 30-day waiting period, although specific exceptions exist, including certain mortgage-related transactions. Private insurance has its own effective-date rules.
Practical example
Suppose a homeowner in northwest San Antonio has a standard homeowners policy but no flood policy. After major rainfall, runoff enters the living room. The owner should not expect standard homeowners coverage to pay for rising-water damage. A separate flood policy could address eligible damage only if it was already effective and its terms cover the loss.
Frequently asked questions
Does being outside a flood zone mean I’m safe? No. All properties have some level of flood risk.
Does flood insurance cover my furniture? Only if you have applicable contents coverage; building coverage alone does not provide that protection.
Where can I check my flood map? Start with FEMA’s official Flood Map Service Center and ask your agent to help interpret the insurance implications.
Flood insurance is best considered before a storm is on the forecast.
Sources: Texas Department of Insurance, flood insurance: https://www.tdi.texas.gov/consumer/storms/flood-insurance.html National Flood Insurance Program, buying a policy and waiting periods: https://www.floodsmart.gov/get-insured/buy-a-policy FEMA Flood Map Service Center: https://msc.fema.gov/portal/home
Coverage reminder: Flood coverage, eligibility, waiting periods, settlement terms, and limits differ by policy. Nothing here guarantees that a particular loss is covered.
Contact Moreno Insurance Agency / TX Agency to discuss flood insurance options for your San Antonio-area home. Call/text 210-256-8576, email [email protected], or visit https://txagency.net.